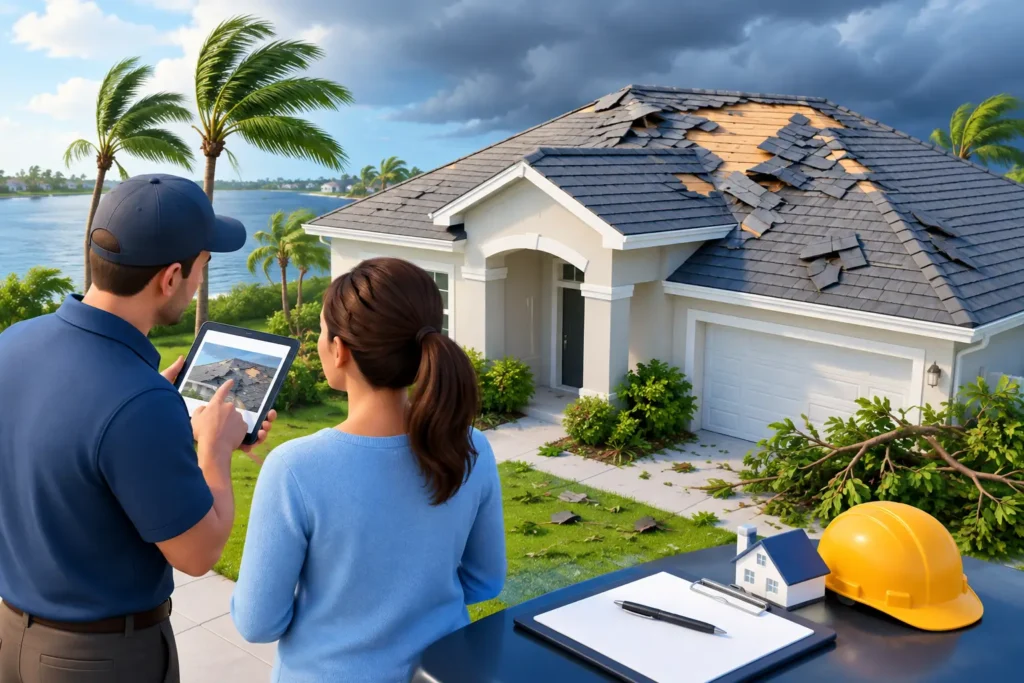
A roof claim often starts on the worst kind of day: water stains spreading across a ceiling, shingles scattered in the yard, or a business taking on water after a hard Florida storm. Knowing how to file a roof claim before the panic sets in can protect your property, your finances, and your ability to get repairs moving without unnecessary delays.
Florida roofs take a beating from wind, driven rain, hail, heat, salt air, and falling debris. But visible damage does not automatically mean an approved insurance claim. The strongest claims are timely, documented, and tied to a covered cause of loss under your specific policy. Here is a practical way to move forward with clear records and no surprises.
Start With Safety and Prevent More Damage
Do not climb onto a storm-damaged roof. Loose shingles, wet underlayment, damaged decking, and downed power lines can make an inspection dangerous. From the ground, look for obvious issues such as missing materials, fallen branches, damaged gutters, exposed areas, or water entering the building.
Your policy generally requires you to take reasonable steps to prevent additional damage after a loss. That may mean placing a tarp over an opening, moving belongings away from a leak, or catching water indoors. Keep every receipt for emergency mitigation, tarping, drying equipment, and temporary repairs. These costs may be relevant to your claim, depending on policy terms.
Avoid permanent repairs until the insurer has had a reasonable opportunity to inspect, unless the work is necessary to stop active damage. Emergency protection is one thing. Replacing an entire roof before documentation and inspection can make the claim harder to evaluate.
Document the Damage Before You Clean Up
Photos and videos create a record of what happened before wind, rain, cleanup, or temporary repairs change the scene. Take wide shots that show the full roofline and surrounding property, then take closer images of each damaged area. If water has entered the home or business, document ceiling stains, wet insulation, damaged drywall, flooring, inventory, furniture, and personal belongings.
Capture the date when possible, and make notes while the details are fresh. Record the approximate time of the storm, what you heard or observed, when the leak began, and which rooms were affected. If a tree limb struck the roof, photograph the limb and the impact area before it is removed if it is safe to do so.
A qualified roofing inspection can also help identify conditions that are difficult to see from the ground, including lifted shingles, compromised flashing, punctures, cracked tile, membrane damage, or moisture intrusion. A roofer can document roofing conditions and provide an estimate for needed work. They should not promise coverage or represent themselves as your public adjuster unless properly licensed to do that work.
Review Your Policy and Know What You Are Claiming
Before calling the carrier, pull out your declarations page and policy documents. Focus on your deductible, roof settlement terms, windstorm or hurricane provisions, exclusions, and reporting requirements. Florida policies vary widely. Some pay replacement cost after certain conditions are met, while others may apply depreciation, special roof endorsements, or actual cash value terms.
The date and cause of damage matter. A sudden wind event, hail strike, or fallen tree can be treated differently than long-term deterioration, wear, prior leaks, poor maintenance, or defective installation. If you are not sure what caused the problem, do not guess. State the facts you know: when you noticed the damage, what weather occurred, and what you observed.
For commercial properties, also review any business interruption, contents, ordinance or law, and water-damage provisions that may apply. A roof loss can affect more than the roofing system. It can disrupt tenants, equipment, inventory, and operations.
How to File a Roof Claim With Your Insurer
Report the loss promptly through your carrier’s claims phone line, website, or mobile app. Have your policy number, property address, date of loss, and a short description ready. Ask for the claim number immediately and save it in more than one place.
When you file, be accurate and concise. Explain the event and the damage you discovered without overstating what you cannot yet verify. For example: “Following the storm on [date], we found missing shingles and water staining in the living room ceiling.” That is clearer and more useful than speculating about the full extent of the loss.
Keep a simple claim file with:
- Your claim number and adjuster’s contact information
- Photos, videos, inspection notes, and weather-related observations
- Copies of your policy and declarations page
- Emergency mitigation invoices and receipts
- Repair estimates, emails, letters, and a log of all calls
After reporting the claim, ask what happens next, whether an adjuster inspection is scheduled, and what documents the carrier needs. Write down the representative’s name, the date, and any deadline they give you. Follow up in writing when possible so there is a clear record of communication.
Be Ready for the Adjuster’s Inspection
The insurance adjuster evaluates the reported loss on behalf of the carrier. Their inspection is an important part of the process, but it is not a reason to stay silent. Be present if you can, share your photos and records, and point out every area where you observed damage or water intrusion.
It can be helpful to have a knowledgeable roofing contractor present during the inspection. The contractor can discuss roofing components, access conditions, repair requirements, and the scope of visible damage. That coordination can reduce misunderstandings, especially with Florida systems such as tile, shingle, metal, modified bitumen, TPO, or coated flat roofs.
Still, there are boundaries. Your contractor can provide an inspection report and repair estimate, but your insurer decides coverage under the policy. If there is a dispute over claim handling or a need for someone to negotiate the claim for you, speak with a qualified insurance professional, attorney, or properly licensed public adjuster.
Compare the Scope, Not Just the Dollar Amount
If the carrier issues an estimate, read the scope of work line by line. A low estimate is not always the main issue. The more important question is whether it includes the work required to restore the roof correctly and in compliance with applicable Florida building requirements.
Look for the roofing material, tear-off, underlayment, flashing, drip edge, ventilation, decking repairs, permits, disposal, and any interior repairs associated with the loss. For tile and metal roofs, matching materials and system-specific details can be especially important. For flat commercial roofs, the scope should address drainage, penetrations, edge metal, insulation, seams, and transitions – not simply the most visible damaged spot.
If your contractor’s estimate differs from the insurance scope, ask for a written explanation of the differences. Supplemental documentation may be needed when hidden damage is discovered during authorized work or when code-related requirements affect the repair. Do not assume a check settles every issue. Read the carrier’s correspondence and ask questions before signing releases or beginning work beyond emergency protection.
Avoid Common Roof Claim Mistakes
The fastest way to make a difficult claim harder is to wait too long. Report damage promptly, even if you are still gathering information. Delays can allow a leak to worsen and can create questions about the cause or timing of damage.
Do not rely on verbal promises from anyone. Keep written estimates, claim communications, and receipts. Be cautious around storm-chasing contractors who appear immediately after severe weather, pressure you to sign paperwork on the spot, or promise a “free roof” before reviewing your policy. A legitimate roofing company should explain the roof condition, the proposed work, the warranty, and your financial responsibilities in plain language.
Also avoid filing a claim simply because a roof is old. Age alone is not a covered event. If the roof has storm damage, document it. If it has reached the end of its service life, a planned replacement with the right system may be the more straightforward path.
Get the Roof Protected While the Claim Moves Forward
Claims can take time, particularly after widespread storms affect Palm Bay and other East Coast Florida communities. That does not mean your property should remain exposed. Arrange reasonable temporary protection, keep records, and communicate with the carrier about any urgent conditions.
A local contractor with Florida storm experience can help you understand the condition of the roof, prepare a clear repair or replacement estimate, and coordinate professionally during the inspection process. Bear Roofing approaches this work with the same standard we bring to every roof: clear communication, code-aware workmanship, and accountability from inspection through cleanup.
Your home or commercial property deserves more than a rushed decision after a storm. Document the facts, file promptly, protect the building from further damage, and choose professionals who will explain the work clearly. That steady approach gives you the best footing for whatever comes next.