A storm can leave a roof looking mostly intact from the driveway while lifted shingles, broken seals, and damaged flashing are letting water reach the layers beneath. This roof replacement insurance claim example shows how a Florida claim may move from a post-storm inspection to a completed replacement, including the numbers homeowners need to understand before signing anything.
The details will vary by policy, storm date, deductible, roof age, and carrier findings. Still, knowing the usual sequence helps you protect your home and avoid a costly mistake: approving a repair or replacement before you know what your policy will pay.
Roof Replacement Insurance Claim Example for a Florida Home
Consider a Palm Bay homeowner with a 2,200-square-foot architectural shingle roof. The roof is 13 years old and had been maintained without active leaks. After a named tropical storm brings strong wind and wind-driven rain, the homeowner notices several shingles in the yard, granules collecting near downspouts, and a fresh ceiling stain in a guest bedroom.
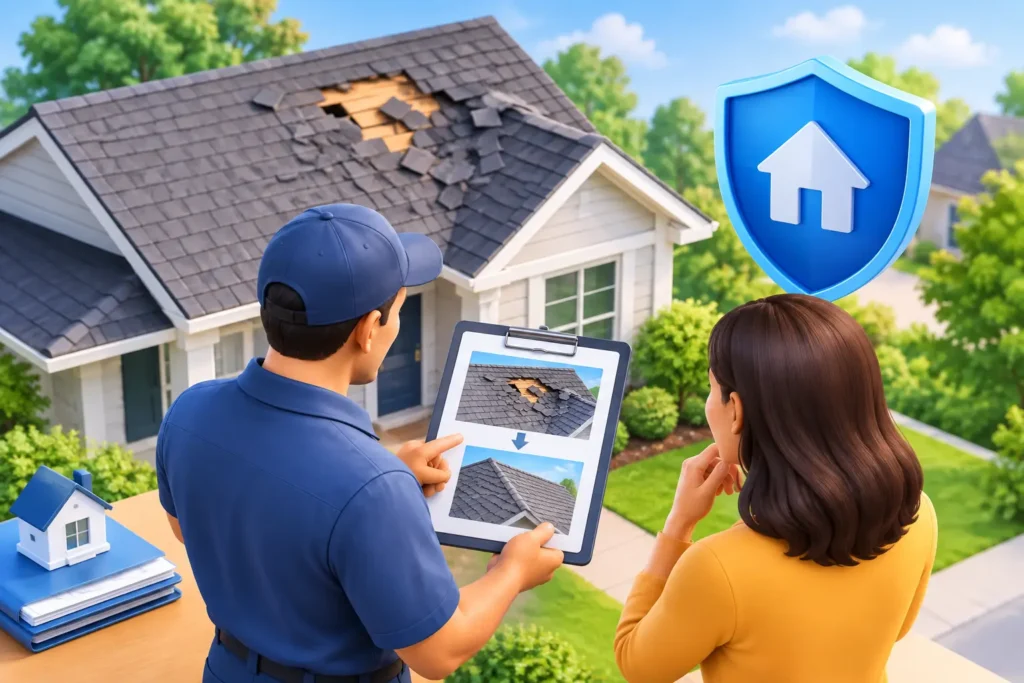
A roofing inspection documents wind-lifted and creased shingles on multiple slopes, exposed fasteners, compromised ridge cap shingles, and damaged flashing around a roof penetration. The inspector also finds that matching the existing discontinued shingle may not be practical. The roof has enough storm-related damage that a full replacement is recommended rather than isolated patching.
The contractor prepares a detailed replacement estimate of $28,600. That figure includes tear-off and disposal, deck inspection, underlayment, flashing work, code-required components, architectural shingles, permits, labor, cleanup, and a final inspection. If concealed decking damage appears after tear-off, that cost may require separate documentation and carrier approval.
The homeowner’s policy has a 2% hurricane deductible based on a $450,000 dwelling limit. The deductible is $9,000. That number matters more than many homeowners realize. A carrier can agree that storm damage occurred and still issue little or no payment if the covered repair amount does not exceed the deductible.
In this example, the carrier adjuster agrees that the storm caused covered wind damage and approves a replacement scope totaling $27,400. The difference from the contractor estimate is reviewed line by line. The contractor’s estimate included upgraded underlayment and additional flashing work needed to meet the roof’s conditions and applicable requirements. With photos, measurements, code information, and a clear explanation of the work, the scope is revised to $28,100.
If the policy provides replacement cost coverage, the carrier may issue an initial payment after subtracting the deductible and recoverable depreciation. Assume the carrier holds back $3,200 in depreciation until the work is complete. The initial calculation could look like this:
- Approved replacement cost: $28,100
- Less hurricane deductible: $9,000
- Less recoverable depreciation: $3,200
- Initial insurance payment: $15,900
After the roof is completed and the final invoice is submitted, the carrier releases the $3,200 depreciation. Total insurance proceeds equal $19,100. The homeowner remains responsible for the $9,000 deductible, plus any elective upgrades not included in the approved scope.
That is a realistic outcome, not a promise. Some policies pay actual cash value instead of replacement cost. In that situation, depreciation may not be recoverable, leaving the homeowner with a larger out-of-pocket amount. Other policies have exclusions, special wind deductibles, limited roof-payment schedules, or strict deadlines for reporting damage.
What Makes This Claim Strong
A roof claim is not strengthened by guesswork or pressure. It is strengthened by evidence. The homeowner in this example reported the loss promptly, took photos after the storm, prevented further interior damage with a temporary tarp, and kept receipts for emergency mitigation. Those actions show the carrier that the homeowner took reasonable steps to protect the property.
The roofing documentation also matters. A useful inspection report identifies the damaged areas, explains the type of damage, includes clear photos, and separates storm-related conditions from normal age-related wear. Florida roofs endure sunlight, heat, salt air, heavy rain, and seasonal storms. An older roof is not automatically ineligible for coverage, but ordinary deterioration is generally not the same as sudden wind damage.
A detailed estimate prevents another common problem: an incomplete carrier scope. Roof replacement is more than shingles. It may involve underlayment, drip edge, flashing, vents, ridge materials, permit fees, tear-off, disposal, decking repairs, and code-related work. When these items are missing, homeowners can be left comparing a low insurance figure against the real cost of a code-compliant roof.
The Claim Process, Step by Step
Start by making the property safe. If water is entering the home, arrange temporary protection and document it. Do not wait for the adjuster before taking reasonable emergency measures, but do not begin a full replacement before the carrier has had an opportunity to inspect unless an emergency makes it necessary.
Next, report the claim directly to your insurance carrier and obtain a claim number. Be accurate about the storm date, what you observed, and when you discovered the damage. Avoid guessing about causes you cannot verify. Your contractor can provide inspection findings, but the carrier makes the coverage decision.
Schedule a professional roof inspection and request a written estimate. If an adjuster inspection is scheduled, having a qualified roofing professional available can help ensure roof-specific concerns are clearly identified. This is not about arguing with the adjuster. It is about making sure the roof system, not just the visible shingles, is evaluated.
When the carrier sends its estimate, compare it carefully with the contractor’s scope. Look for differences in material quantities, tear-off charges, flashing, underlayment, ventilation, permit costs, waste factors, and code items. A lower estimate is not automatically wrong, and a higher contractor estimate is not automatically right. The answer should be supported by measurements, photos, local requirements, and the actual condition of the roof.
If supplemental work is needed, document it before proceeding whenever possible. For example, damaged decking discovered during tear-off should be photographed and described. The same applies to hidden flashing damage or required components not visible during the initial inspection. Good documentation protects both the homeowner and the contractor.
Watch the Deductible and the Fine Print
No contractor should offer to waive, absorb, or hide your insurance deductible. In Florida, the deductible is the policyholder’s responsibility. A legitimate contractor can explain financing options, payment schedules, and the approved scope of work. They should not make the deductible disappear through inflated invoices or side agreements.
Also pay attention to whether your policy uses actual cash value or replacement cost value. Actual cash value generally accounts for age and depreciation from the start. Replacement cost coverage may allow recoverable depreciation after the work is completed, but only if the policy conditions and deadlines are met. Ask your carrier how much depreciation is being held back, what documentation is required, and when it must be submitted.
Matching is another area where expectations can become complicated. If only one slope is damaged, the carrier may initially allow repair on that slope rather than replacement of the entire roof. Whether a full replacement is warranted depends on the damage pattern, material availability, policy language, applicable regulations, and whether a repair can restore a functional roof system. Do not assume matching alone guarantees full replacement.
Choosing the Right Contractor After Approval
Insurance approval is not the finish line. It is the point where workmanship becomes critical. Choose a Florida roofing contractor that can explain the estimate in plain language, pull required permits, follow manufacturer specifications, protect landscaping and exterior surfaces, and provide a written workmanship warranty.
Ask how the team handles decking discoveries, supplements, cleanup, and final documentation. A replacement project should have a defined plan from material delivery through magnet sweeping and final inspection. No surprises. No disappearing act.
Bear Roofing helps East Coast Florida property owners understand storm damage, compare scopes, and complete roof replacements built for the conditions our communities face. The goal is not to promise an insurance outcome. It is to give you clear evidence, honest guidance, and a roof installed with accountability long after the last truck leaves your driveway.
If you suspect storm damage, document what you see, protect the home from further water intrusion, and get a professional inspection before a small issue turns into an interior repair project.